


What lenders look at besides your score
Your credit score is only one part of a car loan application. Here is what else lenders may review, and how to keep your file moving.

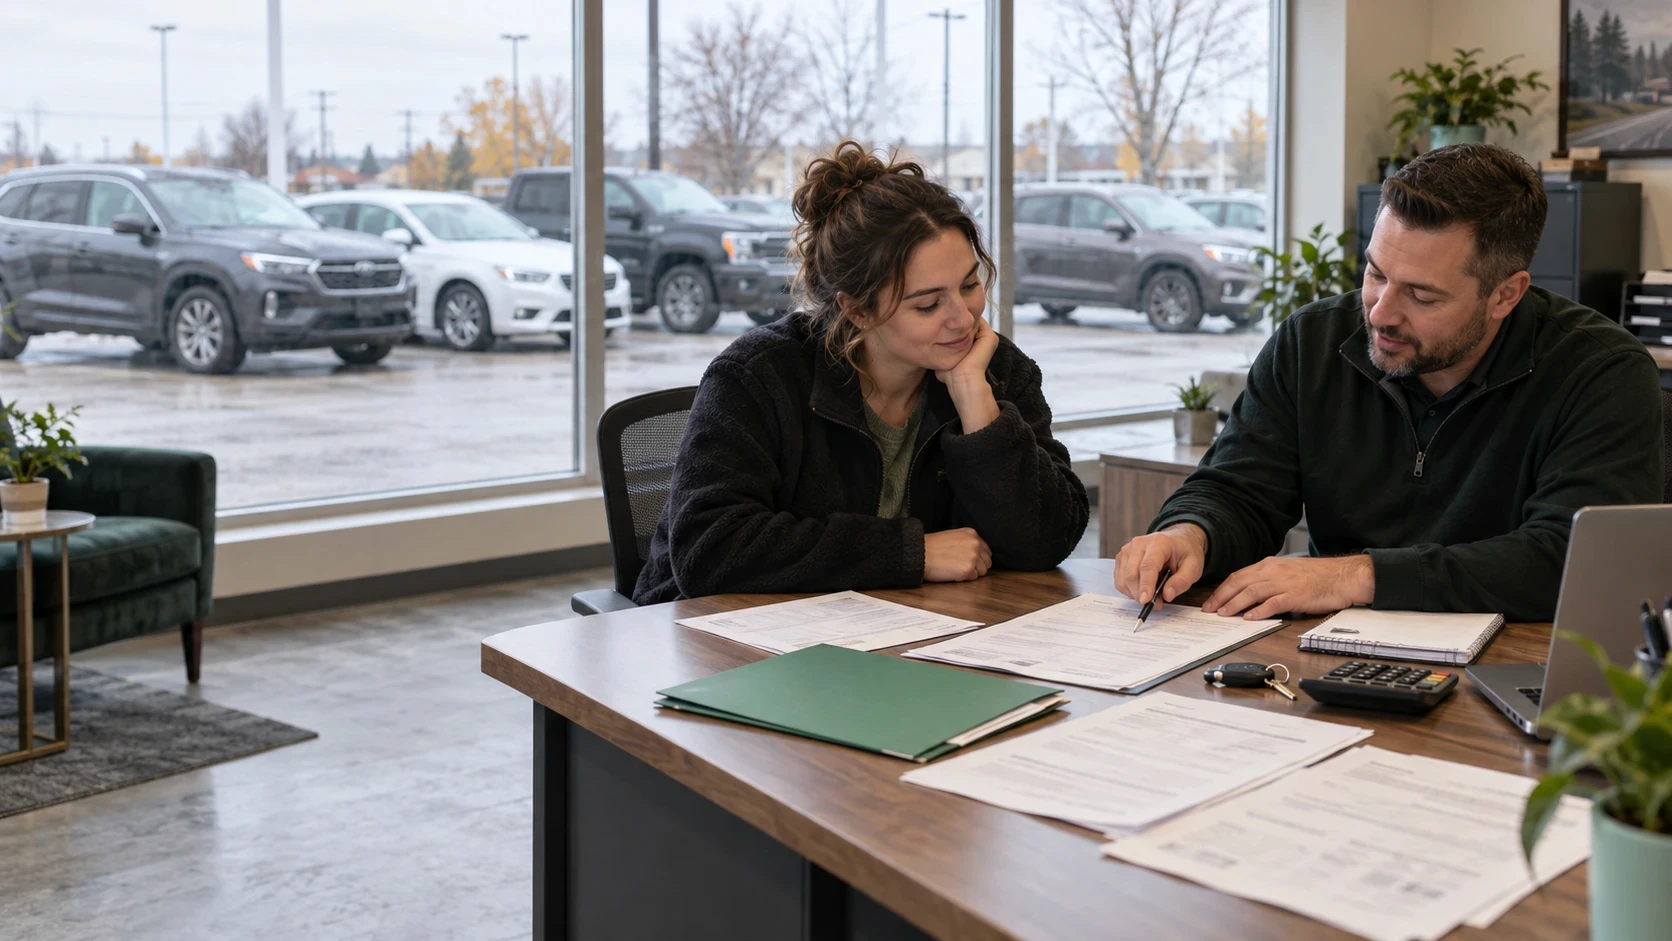
Many people start with their credit score, as if it settles the matter. It does not. A score sums up how credit has gone for you in the past. It does not show everything about your finances today, such as shift work you picked up recently.
Here is what a lender may look at besides your score.
Income
Lenders generally want proof of regular income, according to the Financial Consumer Agency of Canada (FCAC). How steady that income is, and how long you have had it, can affect the answer.
If you receive income such as Employment Insurance, a pension, disability benefits or the Canada Child Benefit, list it on your application and bring documents for it. Each lender decides which income sources it will count.
Stability and existing debts
FCAC says lenders generally want to see a bank account and a permanent address, and will likely consider the debts you already have. That includes regular payments such as rent or a mortgage, other loans and support payments.
Choose a payment that fits your real monthly budget, not just the numbers on paper.
Down payments and trade-ins
A down payment lowers the amount you need to borrow. A trade-in does the same when the vehicle is worth more than you still owe on it. Ask each lender how a down payment would change the offer.
In Manitoba, when you trade a vehicle in to a dealer toward another vehicle, retail sales tax is generally charged on the price after the trade-in value is deducted. Some conditions apply, which we cover in our guide to how a trade-in works in Manitoba.
Does applying affect your credit?
Auto Approved does not pull your credit itself. A lender may check your credit when it assesses your application. Canada has two main credit bureaus, Equifax and TransUnion, and a lender may use either one. FCAC lists how often you apply for new credit as one of the factors in your score, and says checking your own report or score does not affect it.
Ask before anything is submitted on your behalf. In Manitoba, your consent must be obtained in advance in most cases before a credit check is done.
Keeping your file moving
Missing paperwork is one delay you can control. A lender cannot finish reviewing a file while proof of income, such as a pay stub, is still missing.
Gather your documents before you apply. They are all listed in the document checklist.
What happens after you apply
FCAC explains that most dealerships arrange car loans for you with a lender. Your application is reviewed by a lender, and the lender decides whether to approve it and on what terms. Ask about the total cost of the loan, not only the payment.
When you are ready you can start an application online in about two minutes, or read how bad credit car loans work at Auto Approved first. If you would rather ask questions before anything goes anywhere, call 204-781-9992.
Auto Approved has been selling used vehicles in Winnipeg since 2000 and arranges financing through lenders.
Sources
Financial Consumer Agency of Canada: Credit report and score basics
Manitoba: The Retail Sales Tax Act, C.C.S.M. c. R130, s. 2(9)
Manitoba Consumer Protection Office: Your personal credit record
General information only, not financial, legal or tax advice. Lenders make the credit decisions on any financing, and rules, taxes and rates can change, so confirm the details for your own situation before acting.
Back to all articles
Related articles

Financing basics
19 October 2026
What credit score do you need for a car?
Each lender sets its own bar, and your score is one part of what they review. Here is how Canadian credit scores work and what else lenders look at.
Winter driving
13 October 2026
Winter tires in Manitoba: a 2026 guide
The switch is about temperature, not snow. Here is when it happens in Winnipeg, what the MPI Winter Tire Program covers, and what changed on October 1, 2026.
Trading in
18 September 2026
Trading in a car in Manitoba: how it works
How a qualifying trade-in can lower the tax on your next vehicle in Manitoba, what an appraiser looks at, and what to bring.

Ready to see where you stand?
Ten short questions, then a call from the person who read them. No obligation, and nothing goes to a lender until you say so.
312 Nairn Ave, Winnipeg, MB R2L 0W9
Mon to Fri 9am to 6pm · Sat 9am to 12pm · Sun by appointment
(204) 781-9992